
Where table tennis sits in the UK betting market, and what each licensed bookmaker does with it
 Available in US
Current as of 26 October 2026. Operator licence details verified against the Gambling Commission’s public register.
The fastest-paced contest a British bettor can put money on through a licensed bookmaker is not a horse race, a five-set tennis thriller or a six-over Twenty20 collapse. It is a table tennis match, settled in roughly twenty minutes, with the score cycling from love to eleven more times than the eye can comfortably follow. Online table tennis betting has grown quietly alongside Setanta Cup coverage, the WTT Tour and the Olympic return of the sport after its brief stay outside the Games, and a £10 punt on a Setka Cup fixture in Kyiv is now a normal entry in a UK betting app’s in-play list. What follows is a working guide to that market as it stands in 2026: how the matches are scored, what the licensed bookmakers actually offer on them, how the prices are built, what an offer costs the bettor who claims it, and where the sport sits inside the wider British gambling regime. The angle is consequence, not description: every figure on the page points at a decision the reader has to make, and every section closes on what that decision costs.
Working with tipsters and tip sheets without paying the price that usually follows
The most searched question in this corner of the market is not “where do I bet?” but “who do I listen to?”. The honest answer to that is shorter than any tipster would like. A tipster is paid to be confidently wrong, because confidently wrong sells subscriptions; the punter who copies every tip without checking the price, the stake and the market ends up paying the tipster’s rent long before he pays his own. What does follow, when a punter treats a tip as one input among many, is a betting log that survives contact with reality.
Table tennis is a particularly cruel sport for the follower-of-tipsters, because its results carry more variance than almost any other. Sets last roughly twenty minutes and a single service break decides a quarter of them; lower-division events on the WTT, Setka Cup and TT Cup circuits are streamed from converted gymnasiums behind the Iron Curtain where the same handful of players meet each other in the same handful of rooms week after week. Form does exist — a player’s recent record against left-handers, against defensive choppers, against players of a similar reach — but form on this circuit is built from samples of twenty or thirty matches, and a tipster selling “80% strike rate” is usually selling a subsample selected after the fact. The honest move is to log every tip you take, with the price you took it at, and to know within a month whether the tipster earns his fee. Most do not, and most readers know this; what they do not always know is that the discipline of keeping the log changes the punter’s own eye for a price, which is the only edge that ever held up in this market.
The same caveat applies, more sharply, to “AI-driven” prediction services that have sprung up around WTT and Setka Cup fixtures. The fixtures are sparse, the players are not always the same person week to week (TT Cup in particular uses pseudonyms that change monthly), and the training data is too thin for any model to outperform the closing line more than marginally. Use them as one factor among several — head-to-head record, current form, the player’s record on the specific table surface and ball type used — and never as the deciding one.
Strategy writing in this market tends towards bankroll management, because match-by-match model-building is what most readers came in hoping for and what almost none of them end up doing. A unit stake of one to two per cent of the bank on any single match keeps a losing streak alive long enough for the punter to learn anything; level stakes across the same fixture list let variance settle to its true mean; and a written record of every bet, settled or void, is the single habit that separates punters who last more than a year from those who do not. That is the strategy. Everything else is a tip sheet with a longer shelf life.
Markets, odds and prices on a table tennis match
What the licensed bookmakers actually offer on a table tennis fixture is narrower than on football but wider than on darts. Standard markets on the main WTT, Olympic and ITTF World Championships events sit across match winner (the most liquid of all of them), handicap (typically a set handicap at the bigger events, a games handicap on the women’s tour), total points (over/under a line in the 18.5 to 20.5 range, where 19.5 is the most common cut-off on a best-of-five match), set winner on individual sets inside the match, and a small set of player props at the bigger tournaments. Live markets mirror most of those once the match has started; markets on the next-point winner and next-server-to-win are routine at the bigger events and absent or thin at the Setka Cup level.
Odds are quoted in decimal form in every UK-licensed app, with the fractional equivalent (5/2, 11/4, evens) shown beside it as a courtesy to long-standing customers. The conversion is mechanical: fractional a/b in decimal is a÷b+1, so 5/2 becomes 3.50 and 11/4 becomes 3.75; odds-on prices shorter than evens (1/2, 4/6) sit between 1.00 and 2.00. The price is the single number that matters: it is the multiple of the stake that comes back if the bet wins, and it carries, inside it, the bookmaker’s margin on the market. A two-way match-winner market where the prices on both sides add up to more than 100% — quoted as a percentage — is a market where the bookmaker is guaranteed profit; a market where the prices sum to exactly 100% would be a fair game, and no licensed bookmaker anywhere runs one of those for long.
To see the margin sitting inside a price, take a worked example. A two-way market where both players are priced at 1.90 (which in fractional form would be 9/10) gives a payout share of 1 ÷ (1/1.90 + 1/1.90) = 1 ÷ 1.0526 = 0.95, or 95%. The bookmaker’s margin is 100% − 95% = 5%, and that 5% is what the licensed operator keeps on every unit the market takes, before staff costs, the levy and General Betting Duty. The same calculation on a three-way market (the outright winner of a small tournament) gives a smaller payout share for the same individual prices, because three implied probabilities add up further; and on a player-props market where the only choice is “over or under 19.5 total points”, the margin compresses to a couple of per cent because the outcome space is small enough for the bookmaker to be confident in the line. The narrower the market, the keener the margin tends to run; the wider the field, the heavier the overround. That is the part of the price the punter cannot change and rarely sees, and it is the part that decides, in the long run, whether betting on table tennis costs him or pays him.
Combined bets work the same way as in any other sport. The odds of two legs multiply into one price, so a £10 double at 1.90 and 2.20 returns £41.80 if both win, with a profit of £31.80; the punter pays no additional margin on the combination beyond the margins sitting inside the two individual prices, but he does give up the ability to cash out one leg independently and he accepts that one losing leg voids the whole stake. Bet Builders on table tennis work the same way as on football: the bookmaker prices the combination as a single bet rather than letting the punter assemble it from individual prices, and the price it offers is almost always worse than the price the punter could build from the same legs. That gap is the bookmaker’s margin on the Builder market, sitting inside a product the marketing calls “build your own bet”. Each-way betting is rare on table tennis because there is no place market in the racing sense; the rule-of-four each-way bettor finds on a Saturday horse race does not exist on a Setka Cup fixture.
A small point worth stating plainly: a price is a promise about a future event, and the promise only matters if the punter can collect at the end. The British licensing regime makes that promise reliable in a way offshore books do not. A GB-licensed bookmaker’s odds are not, on the whole, sharper than an offshore book’s, but the GB punter knows who pays him when he wins, and he knows where to complain if he is not paid. That knowledge is the part of a price that does not appear on the betting slip.
Tournaments, fixtures and the calendar that drives the market
Table tennis does not have a Premier League. The closest the sport comes to one is the WTT Tour, run by World Table Tennis out of its Singapore headquarters, which stages WTT Contender and WTT Champions events across Asia, Europe and the Americas through most of the calendar year. The Olympic and World Championships sit at the top of the pyramid, with the World Championships held in odd years between Olympics; continental championships (the European Championships, the Asian Championships, the Pan American) sit just below them, and the ITTF-run team events — the World Team Championships and the mixed-team equivalent — sit alongside.
For the punter, the practical calendar is shorter than the official one. The licensed bookmakers in this list price up WTT events comprehensively and ITTF events most of the way; they list the Setka Cup, TT Cup and WTT Star Contender feeders in the in-play menu but with thinner markets and longer suspensions during play; and they do not, on the whole, price up national league fixtures outside the United Kingdom, because the volume does not justify it. A typical week on the licensed market looks like three or four WTT events, a Setka Cup stream running most evenings from Eastern Europe, and any team competition currently in progress. The quiet weeks are the dead weeks of the football calendar too, and the punter who treats table tennis as a year-round interest ends up betting more than he means to on the lower-division streams.
The most-watched event in the cycle, from a British punter’s perspective, is the Olympic table tennis tournament, which the BBC streams and the bookmakers price up comprehensively from the group stage. The Paralympic equivalent is also streamed and priced. World Championships finals get terrestrial coverage on Eurosport and discovery+; WTT events sit behind a paywall on the WTT app. None of that coverage is required for a bet — the bookmaker’s in-play console runs on its own data feeds — but it tightens the punter’s sense of form, which is the only edge the market grants its participants.
The licensed shortlist: how ten UK bookmakers actually handle table tennis
Ten bookmakers hold the relevant Gambling Commission licence and price up table tennis at the level this guide covers. The comparison below cuts to what each of them does with the sport, rather than to a generic ranking; a brand that runs a thin in-play offer on table tennis but a deep one on football is not a poor table tennis bookmaker — it is a different bookmaker, and a punter who wants the sport covered well should know which is which before he opens an account.
| Brand | Licence status | What the operator’s terms say about table tennis |
|---|---|---|
| Betway | Gambling Commission remote licence 039372-R-319367-029; licence holder Betway Limited | Prices up WTT events and the Setka Cup feed; same-game-multi / Bet Builder on selected match-ups; in-play console covers match winner and next-game winner; minimum stake rules and the Free Bet Club conditions sit in the sportsbook’s general terms. |
| Dabble | Gambling Commission remote licence 065677-R-340363-005; licence holder Dabble Sports UK Ltd | WTT and Setka Cup priced; in-play markets thin but functional on the better-supported events; new-customer offer applies to any sport with a minimum odds restriction; seven-day free-bet expiry on promotional stakes. |
| Spreadex | Gambling Commission remote licence 008835-R-104580-022; licence holder Spreadex Limited | Combines fixed-odds and spread betting on one licence, so the same screen shows match-winner odds and a points-spread market; Bet Builder works across fixed and spread selections; live streaming covers tennis, NFL and selected football but not table tennis; financial regulation by the FCA applies to the spread side. |
| bet365 | Gambling Commission remote licence 055148-R-331498-002; licence holder Hillside (UK Sports) ENC | The depth benchmark on WTT and Olympic fixtures; Bet Builder+ combines markets on a single match into one priced bet, available pre-match and in-play; in-play console carries next-game and next-point markets on the bigger matches; live streaming policy is the operator’s own. |
| Smarkets | Gambling Commission remote licence 039173-R-319366-011; licence holder Smarkets (Malta) Limited | Runs as a betting exchange, so customers back and lay against each other at prices they set; commission applies on net winnings; in-play depth depends on what other customers are offering rather than a house margin; deposit and withdrawal terms are the operating licence terms. |
| Bet600 | Gambling Commission remote licence 044731-R-323941-016; licence holder Tyche Tech Limited | Priced primarily for the more popular UK-facing sports; table tennis appears in the menu but the in-play console is thinner than the leader’s; operator terms cover minimum-stake, maximum-stake and maximum-winnings rules in the sportsbook’s general section. |
| BoyleSports | Gambling Commission remote licence 039469-R-319383-025; licence holder Boylesports Enterprise | UK-facing sportsbook with the standard WTT and Setka Cup feed; in-play console covers the usual markets; new-customer offer applies across the sportsbook with sport-specific terms in the campaign’s small print; debit-card-only deposit policy under credit-card ban is unchanged. |
| Betfair | Gambling Commission remote licence 039439-R-319330-013; licence holder PPB Counterparty Services Limited | Runs both the exchange and the sportsbook under the same GB licence; the sportsbook duplicates the leader’s WTT coverage with Bet Builder, free live streaming of selected events and a 90-minute payout market on football that does not extend to table tennis; commission terms on the exchange sit in their own section. |
| NetBet | Gambling Commission remote licence 039170-R-319343-032; licence holder Netbet Enterprises Limited | Sportsbook-and-casino combination; Daily Boost and Profit Boost tokens apply to selected table tennis matches; Bet Builder pricing is marked “instant dynamic odds” in the operator’s own terms; sports stat pages cover the major leagues but not, in this guide’s reading, the WTT tour in depth. |
| Swifty Sports | Gambling Commission remote licence 058957-R-334734-006; licence holder Swifty Global (UK) Ltd | UK-facing bookmaker with Best Odds Guaranteed on horse racing; table tennis is on the menu but the same depth of in-play market as the WTT-specialist books is not established; Cash Out covers football and racing outright markets; Bet Builder is described in the app’s listing as “coming soon” rather than active. |
What the table does not say, and what the punter has to take from the prose around it, is that depth on this sport is not evenly distributed. bet365 and Betfair (on the sportsbook side) are the depth benchmarks on WTT and Olympic fixtures: their consoles carry next-game and next-point markets on most matches, and the Bet Builder combines markets on a single match into one priced bet. The Setka Cup stream is a different proposition — most of the licensed operators carry it, but few of them run a rich in-play console on a third-tier match in a converted gymnasium in Eastern Europe, because the data feed and the trading team are not always there to support it. Smarkets and Betfair Exchange do not have a “house depth” on any sport in the conventional sense: their prices are whatever customers are prepared to back and lay, and the punter who can hold his nerve on a thin exchange book can sometimes find better prices than the sportsbooks quote. Spreadex and Swifty Sports carry smaller product catalogues, and a punter who already has an account with them for football or horse racing should expect a thinner, but still licensed, offering on table tennis rather than a peer of the leader’s. Each of the ten is a real choice for a real reader; what differs is what they are best at.
The honest read across the ten is that bet365 is the most complete bookmaker for a punter who follows WTT events closely enough to want next-point markets, and that the betting exchanges (Smarkets and Betfair Exchange) suit a punter who can name his own price and wait for someone to take the other side. Dabble, BoyleSports and NetBet are competent mid-market sportsbooks whose table tennis offering mirrors their football one: present, functional, but not differentiated. Swifty Sports and Bet600 carry the sport in their menu without running the depth of console that a serious in-play bettor expects; they suit a casual interest better than a daily one. Spreadex is the unusual case, because its licence combines fixed-odds with spread betting on the same platform, and a punter who wants spread-side markets on table tennis points rather than match winners has nowhere else on the comparison list to find them.
Statutory frame and what a Commission licence actually buys a punter
Great Britain has no list of permitted sports or permitted markets. A bookmaker that wants to take a bet from someone in England, Scotland or Wales needs a Gambling Commission licence, and the Commission’s public register — searchable by business name, trading name, domain or account number — is the whole test of who holds one. The regime sits on the Gambling Act 2005 and its 2014 amendment; the Gambling (Licensing and Advertising) Act 2014 made it compulsory, at the point of consumption, for an operator to hold a Commission licence wherever the operator itself is based, so a Curaçao, Maltese or Gibraltar licence is no longer enough to serve a British customer. That is the regime’s central feature, and the one that distinguishes a licensed British bookmaker from a perfectly legal bookmaker based in another jurisdiction that is also perfectly illegal to use from a sitting room in Manchester.
The licence categories matter for what an operator is allowed to offer. The books on this list mostly run under “remote general betting standard (real events)”, which is the broad licence covering real sporting contests; Smarkets runs as a “remote betting intermediary”, which is the licence for a betting exchange, and Betfair’s sportsbook runs the general betting licence while its exchange runs the intermediary one. The difference matters at the operational level — an exchange carries back and lay markets, charges commission on net winnings, and runs no house margin in the conventional sense — but for the punter the practical fact is the same: the Commission licence covers the activity, and the public register entry is the proof. Financial spread betting, where the liability can exceed the stake, is regulated by the Financial Conduct Authority, which is why Spreadex sits in both registers.
What the licence actually buys a British punter is the suite of consumer protections that come with it. The bookmaker must verify name, address and date of birth before the customer can deposit or place a bet (that rule has applied to free bets and bonuses as well as to cash stakes since 7 May 2019). Every online operator takes part in GAMSTOP, the national multi-operator self-exclusion scheme, and a customer who has self-excluded through GAMSTOP is blocked from opening new accounts at every licensed operator for the period of his exclusion (six months, one year, five years, or five years with auto-renewal). Wagering requirements on bonuses are capped at 10x — a £10 bonus at 50x wagering is unlawful; the cap means the punter is never asked to bet more than £100 to clear a £10 bonus. Mixed-product promotions that require gambling on two or more product types — for example “bet on football to get free spins” — are banned since 19 January 2026. A financial vulnerability check applies once a customer’s deposits minus withdrawals exceed £150 in a rolling 30-day window, and it is a public-record check (bankruptcy, county court judgments) rather than an income check or a credit reference check. Beyond those, the operator offers its own deposit limits and the punter can set his own. None of these protections is strictly required at an offshore bookmaker, and that is why a GB punter’s first test of a brand is the Commission’s register rather than the marketing email.
The honest framing on offshore books is that a Curaçao-licensed brand is not illegal for the British punter to use, but the British punter gives up every protection listed above if he does. There is no GAMSTOP coverage at an offshore bookmaker, no Commission complaints route, no ADR-approved dispute-resolution service, no obligation to honour a bonus under the 10x cap, and no recourse if the operator declines to pay out a winning bet. The regulator’s response when an unlicensed bookmaker targets British customers is disruption (cease-and-desist notices, work with payment providers, search-engine referrals) rather than blocking — the court-order DNS blocking powers the Commission has been given are not the same as a working ISP block, and writing “blocked at the border” is wrong. The frame is unlicensed = none of those protections and possible loss of funds, and that is the frame that holds up.
Responsible gambling and the limits a punter can set without asking
The British regime assumes the punter will set his own limits, and the licensed operator offers the controls to do it. GAMSTOP, deposit limits, time-outs and full self-exclusion are the four the punter usually meets; the regulator’s own statutory framework requires an operator to offer each of them, and a customer who has set a deposit limit cannot increase it without a cooling-off period that gives him a chance to change his mind. The licensed operators on this list each take part in GAMSTOP and each carry the safer-gambling controls in their account menu.
The new rules layered on top of those controls are the ones a 2026 punter needs to know about. A financial vulnerability check applies once a customer’s net deposits exceed £150 in a rolling 30-day window: it is a public-record check rather than a credit check, and it is the operator asking whether anything in the customer’s recent financial record makes continued play unsafe. A second phase — financial risk assessments, more colloquially “affordability checks” — has been announced, staged, with no start date; writing it as if it were in force is wrong, because the Commission’s own article on the matter dates the announcement and gives the stages without tying them to a calendar. A deposit-limit regime (RTS 12) is in force in part: the first phase of changes has applied since 31 October 2025, a second phase has been postponed to 30 September 2026, and whether the second phase is now live is not something this guide can establish. None of those rules imposes a state-set ceiling; the only ceiling that exists is the one the punter sets himself on the operator’s own account page.
Help, when help is needed, is the practical matter. GamCare runs the National Gambling Helpline and a network of local counselling services; the NHS runs problem-gambling clinics in most regions of England; Gamblers Anonymous runs peer-support meetings. The licensed operators carry links to each. The gambling trade body, the Betting and Gaming Council, runs an alternative dispute resolution service for unresolved complaints at its member operators. None of those routes exists at an unlicensed brand; that is the route the licence buys.
Cryptocurrency, e-wallets and the question of paying without a paper trail
The short answer to “can I bet on table tennis with bitcoin at a licensed UK bookmaker?” is that this guide cannot establish one. The British licensed regime has no statutory rule for or against cryptocurrency deposits, and the operators on this list each carry their own payment-methods page rather than a sector-wide rule. What the licence does require is name, address and date-of-birth verification before the first deposit, which makes genuinely anonymous play at a licensed site impossible. A punter funding an account with a regulated UK debit card or via open banking is going through full CDD under anti-money-laundering rules; a punter funding it with a credit card cannot, because credit cards are banned for gambling in Great Britain (LCCP condition 6.1.2), including credit-card-funded e-wallet top-ups.
What the licensed operators do offer, in practice, is a payment-methods menu that runs through debit cards, bank transfer and the regulated UK e-wallets, with deposit and withdrawal limits set by the operator. Smarkets’ published terms, as the one example this guide can name with figures, are instant deposits from £10 to £10,000 on open bank transfer and instant from £10 to £15,000 on UK debit card, with withdrawals processed inside six hours on amounts from £10 to £100,000. Each operator on the comparison carries its own version of those limits. A punter who wants the speed of an e-wallet withdrawal and the small-stake-friendly limit does best to read the operator’s payments page before opening an account, because the published number is the one the punter has to plan around.
The honest read on cryptocurrency betting is that it exists at offshore books, which accept bitcoin and a handful of other coins and which do not run a GB licence, with the consequences covered in the statutory frame above. A punter who wants crypto deposits can find them; a punter who wants crypto deposits and a British licence, on the data this guide has, has to settle for the licensed book and the regulated payment method. The two products do not, in this market, sit on the same shelf.
Bonuses and free bets on table tennis, and what the marketing word actually costs
The British licensed operator’s bonus offer looks generous on the page and usually narrower in the small print. The 10x wagering cap is the headline rule: a £10 bonus cannot require more than £100 of bets to clear, and a £50 bonus is capped at £500 of bets. The cap sits on the bonus, not on the free bet where the stake is not returned — those are mechanically different offers with different maths. Mixed-product bonuses are unlawful as of 19 January 2026, so “bet on football to get free spins” style promotions are gone. New-customer offers on the comparison come in three shapes: a matched first bet (Dabble’s “Bet £10, Get £10 in Free Bets” being the cleanest example), a free-bet bundle contingent on a weekly spend (Betway’s Free Bet Club paying up to £10 weekly once a £25 wager has been placed), and a stake-back / insured-bet free-bet on a losing first wager (Betfair’s sportsbook and BoyleSports among those using the device). Each of those offers, translated into a number the punter can work with, carries a stake condition, a minimum-odds condition, an expiry and (usually) a free-bet stake-not-returned clause.
The maths of a “free bet” worth £10, with the stake not returned, at odds of 3.00 (2/1) is straightforward. The value of the free bet, on average, is the free-bet amount multiplied by (odds − 1) ÷ odds. At 3.00 the £10 free bet is worth £10 × 2 ÷ 3 = £6.67 on average before the market margin is layered in; layered in, the value falls further, because each leg of the rollover is itself priced with the bookmaker’s margin sitting inside. The £10 free bet the marketing calls a £10 free bet is, on average, closer to £6 in the punter’s pocket after the conditions are honoured. A “matched” bonus works on different maths, because the bonus is paid as withdrawable cash subject to rollover rather than as a free bet whose stake is not returned, and the rollover is capped at 10x. The £10 bonus on a £10 deposit, with 10x rollover and minimum odds of 1.50 (1/2), requires £100 of bets at 1.50 or longer. The margin a sportsbook carries on a 1.50 market is, broadly, 7–8%, so the expected cost to the punter of clearing the bonus is roughly £7 to £8 — close to the £10 face value, which is the point. No bonus is an arbitrage, and a punter who treats them as such is paying the bookmaker for the privilege of being wrong more often than not.
What a punter reading the table and the small print should take away is the same point the operators’ own terms make. There is no bonus that pays more than the bonus’s face value, in expected terms, and there is no offer on which the marketing line (“free”, “risk-free”, “guaranteed”) outruns the actual cost the punter will pay to clear it. The 10x cap is the most punter-friendly part of the British regime and the one no offshore bookmaker is bound by. A punter claiming a licensed-operator offer is paying within the cap, which is the position a sensible bettor wants to be in; a punter claiming any number of offers without reading the conditions is paying more than that, and the offer is the smallest part of what he is paying.
Live betting, cash out and the way table tennis moves underneath an open bet
Table tennis is, alongside tennis, darts and badminton, one of the few sports an in-play console treats as a continuous market rather than a clock-stopped one. Points flow; the score cycles; the lead changes hands every few rallies. A licensed UK bookmaker’s in-play offering on a WTT match covers match winner (live, retraded on every point), next-game winner, total points over/under, and — at the bigger consoles — next-point and even handicaps on the in-game score. The punter who has the match open on a stream alongside the betting app is closer to the data than the operator’s trader in some cases, which is the single structural reason in-play betting on this sport is interesting.
Cash out is the licensed operator’s tool for closing a bet before the event has settled, and the way it is priced on table tennis deserves a sentence. Bet365, Betfair, BoyleSports, Spreadex and Swifty Sports (among others) carry cash out on selected table tennis markets; the cash-out price the operator offers mirrors what the live market would offer on the same selection, less the bookmaker’s margin on the cash-out transaction. The margin on a cash-out transaction is usually wider than the margin on the original bet, because the operator is taking one side of a trade the punter was not asking to make. A punter who uses cash out as a discipline tool — locking in profit on a winning position, cutting a loss on a losing one — pays the margin twice, once on the original bet and again on the cash out; a punter who lets the bet settle pays only the original margin. Cash out is a useful tool in particular circumstances; the small print that says “margin applies” is the bit the small print ought to say.
Bet Builder on a table tennis match works the same way as on a football match in operator-consoles that carry it. The punter combines markets — match winner, total points, first-game winner — into one priced bet, the operator prices the combination (usually wider than the punter could assemble from the individual legs), and the bet pays as one bet at one price. On bet365, Bet Builder+ extends to in-play combinations; on NetBet the Builder carries “instant dynamic odds”. The device is functionally a same-game multi, and the maths is the same: the operator’s margin sits inside the builder price, and the punter gives up the option to cash out individual legs in exchange for the higher headline odds on the combination. It is not, on average, a cheaper way to bet on table tennis; it is a more convenient one.
Live streaming is the piece of the package the operators each describe differently. bet365 streams events worldwide across its licensed book; Betfair offers free live streaming of selected events; Spreadex streams UK and Irish horse racing, greyhounds, tennis, NFL and selected football from its app, but not table tennis on the data this guide carries. Where a stream is available to the punter, the stream is the closest substitute for a data feed he can see with his own eyes; where it is not, the punter is betting on whatever the operator’s console tells him is happening, which is the structural reason in-play depth on the Setka Cup feed is thinner than on the bigger events. The reader who plans to bet live on table tennis should plan for the stream first and the bet second.
The geometry of a table tennis match
The sport itself is short and settled by narrow margins, and the betting markets inherit both features. A table tennis game is won by the first player to reach 11 points, and if both players reach 10, the first to lead by two points wins the game. A match is the best of any odd number of games, with competition matches typically best of five or best of seven. Service alternates every two points until both players reach 10; once both have done so, service alternates after every point. The scoring system changed from 21 points per game to 11 in 2001, and the change is the reason 1980s-era records of men’s table tennis look more lopsided than modern ones — a 21-point game had more room for a comeback than an 11-point one does.
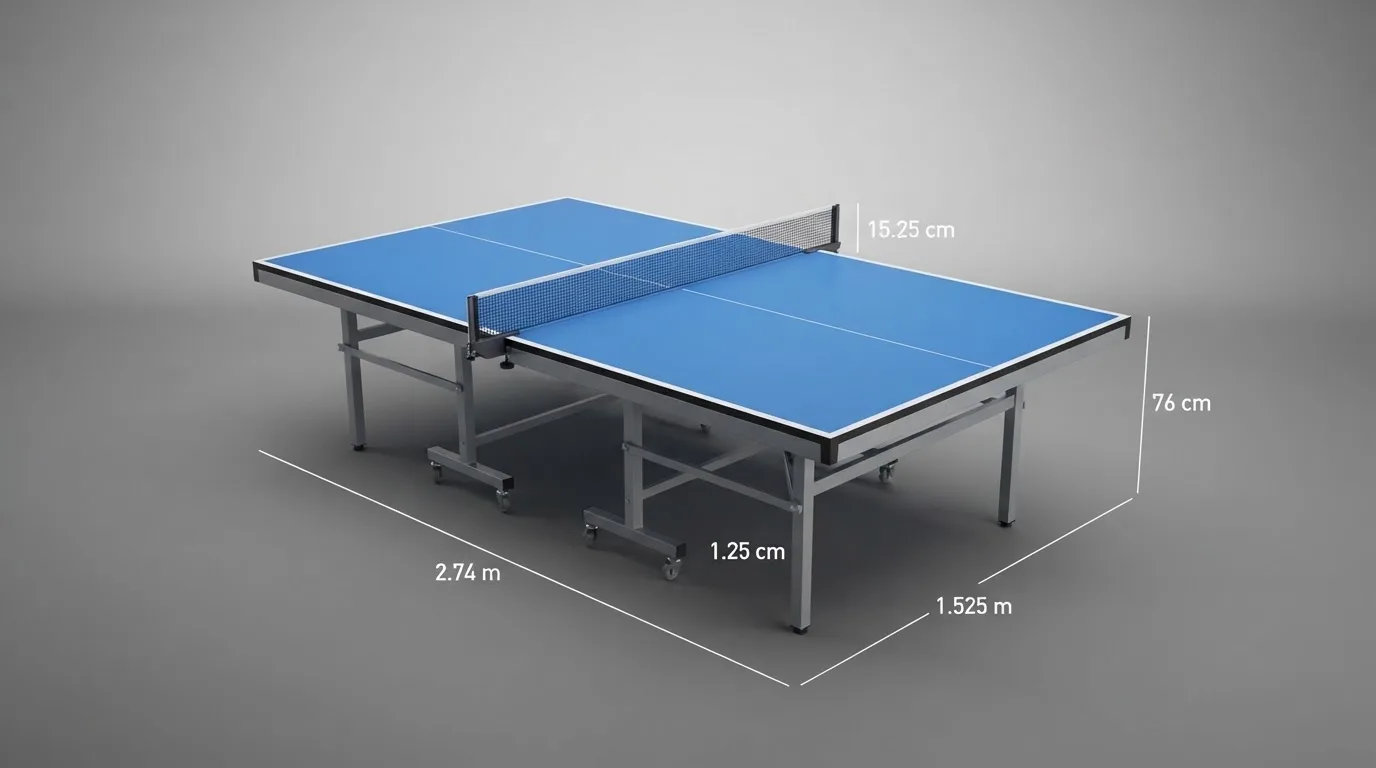
The playing surface is fixed by the ITTF: the table is 2.74 m long, 1.525 m wide and 76 cm high, the net stands 15.25 cm high, the ball is 40 mm in diameter and weighs 2.7 g. Those dimensions sit at the foundation of the sport’s geometry, and they are the reason a Setka Cup fixture resolves in roughly twenty minutes and a best-of-seven Olympic final in roughly ninety. The bettor who watches the sport notices the rhythm: deuce games run longer, service breaks decide more games than skill differential does at the lower-division level, and the lead at the first technical timeout of any game is a better predictor of the result than the head-to-head record is. None of that is a tip; it is the geometry the markets are built on.
The international federation is the International Table Tennis Federation (ITTF), founded in 1926, and table tennis has been on the Olympic programme since 1988. The professional era that the punter sees today — WTT, ITTF World Championships, the Olympic and Asian Games showcases — runs on the back of a federation that has run the sport for a hundred years. A punter who treats the sportsbook as the world of table tennis is seeing the same fixtures the federations stage; a punter who treats the federation as a marketing partner of the operator is misreading the relationship, which runs the other way.
Final word before the page closes
The market in 2026 is wider than it was three years ago and narrower than the marketing emails suggest. Ten licensed bookmakers take table tennis bets from a British punter; some of them run rich in-play consoles on WTT events and a thin one on the Setka Cup feed, and others run the opposite. A punter who wants the depth should pick on that basis; a punter who wants the bonus should pick on the maths, not the headline. Both choices are reasonable, and both choices are made more sensible by a working understanding of how a price is built and what an offer actually costs. The rest of this page is the questions readers ask first, and the answers that hold up to the figures on the page above.
Frequently asked questions
How to win at table tennis betting?
There is no system that wins at table tennis betting, and a tipster selling one is selling access to variance he cannot forecast. The habit that holds up over a season is keeping a written record of every bet with the price and the stake, betting one to two per cent of the bank on any single match, and letting a hundred or so bets settle before judging whether the strategy earns anything. Most strategies do not, and most punters who keep the log know that within a month. The log is the strategy.
How do you bet on table tennis?
Open an account with a bookmaker listed on the Gambling Commission’s public register; complete the name, address and date of birth verification the licence requires; deposit with a UK debit card or open-bank-transfer method (credit cards are banned for gambling in Great Britain); choose the match, the market and the stake; confirm the bet. The licensed operator settles the bet when the match finishes and pays withdrawals to the same payment method, with the operator’s own deposit and withdrawal limits published in its terms.
How is a table tennis bet placed?
Same as any other fixed-odds bet: pick the selection, enter the stake, confirm. In-play bets work the same way after the match has started, with prices retraded on every point in the busier consoles. Combination bets (a double, an accumulator, a Bet Builder) are placed as one priced bet rather than as several separate ones; the price of the combination is the product of the individual prices, less the operator’s margin on the builder.
How can a bookmaker’s Gambling Commission licence be checked?
The Commission’s public register at the regulator’s own web address is searchable by business name, trading name, domain or account number. The ten operators on this page each carry an entry on the register under the licence numbers in the comparison table above. The register entry is the whole test of whether a brand holds a Commission licence; anything a marketing email says to the contrary is marketing. The Commission’s public register is a public record.
How is the return on a bet worked out from the stake and the odds?
Decimal odds: return = stake × odds; net profit = stake × (odds − 1). A £10 bet at odds of 1.90 returns £19.00 (a net profit of £9.00); the same stake at 3.50 returns £35.00 (a net profit of £25.00). Fractional odds a/b in decimal are a÷b+1, so 5/2 becomes 3.50 and 11/4 becomes 3.75. For a combination bet, multiply the decimal odds of each leg together to get the combined price; a double at 1.90 and 2.20 is a combined price of 4.18.
What is the bookmaker’s margin and how is it visible in the odds?
The bookmaker’s margin is the share of every unit bet on a market that the bookmaker keeps on average; it is the difference between 100% and the payout share of the market. Payout share = 1 ÷ (1/odds₁ + 1/odds₂ + …) over every outcome of a single market; margin = 1 − payout share. On a two-way market priced at 1.90 and 1.90, the payout share is 95% and the margin is 5%. The margin is the part of every price that is the bookmaker’s, and a punter who wants to know where the bookmaker earns on table tennis reads the margin on each market rather than the headline price.
Tennis, darts & cue sports – AI Betting
Content created by the «AI Betting» team
